
If you receive Social Security Disability Insurance when you reach full retirement age, Social Security normally changes the benefit to a retirement benefit automatically. The monthly amount generally stays the same.
However, that simple rule leaves several practical questions: Do you apply again? What happens to Medicare? Can you work? Do medical reviews stop? What if you claimed reduced retirement while waiting for a disability decision? This guide follows the transition in the order it happens.
The five-second answer
- The conversion is automatic at your Social Security full retirement age.
- You do not receive SSDI and retirement on the same earnings record at the same time.
- Your monthly amount generally does not change merely because the benefit name changes.
- Your full retirement age depends on your birth year. It is 67 for people born in 1960 or later.
- SSI is different. Supplemental Security Income does not automatically become a Social Security retirement benefit.
First, make sure you mean SSDI
Social Security Disability Insurance (SSDI) is based on your work record and Social Security-covered earnings. Supplemental Security Income (SSI) is a separate, needs-based program with income and resource limits. In some cases, people receive both.
Therefore, the automatic conversion discussed here applies to SSDI. By contrast, if you receive SSI, your eligibility can continue after retirement age if you still meet its financial and other rules. If you receive both programs, read each notice carefully because one part may change while the other continues.
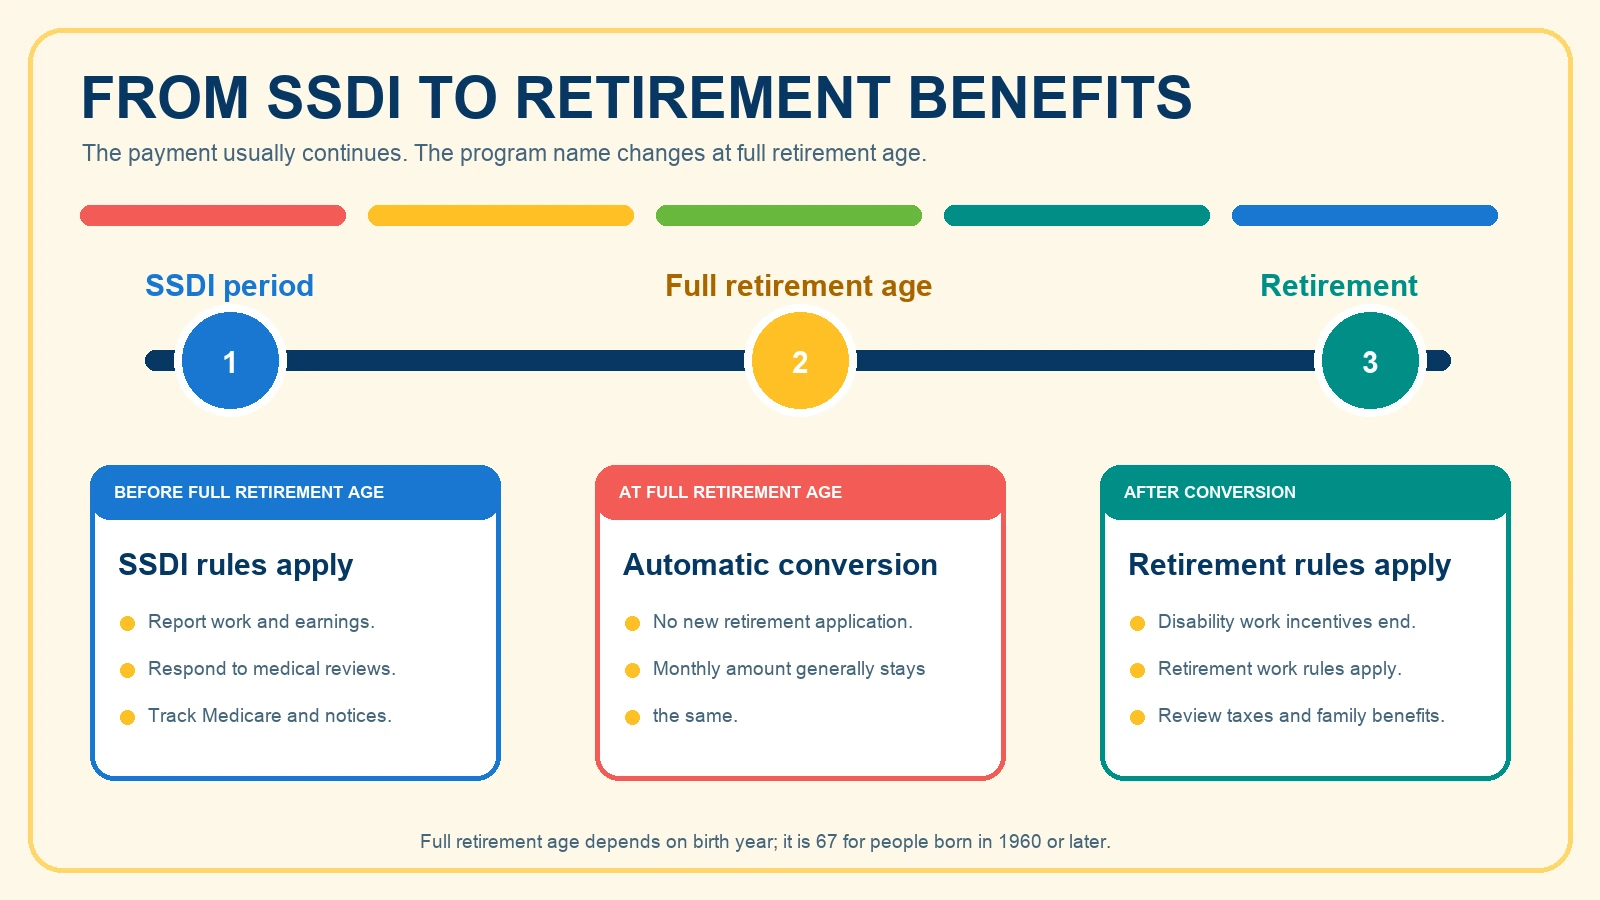
Your transition has three stages
1. Before full retirement age
You remain an SSDI beneficiary. Disability medical rules, work incentives and reporting duties still matter. In addition, Social Security may conduct a continuing disability review. Report work, wages, self-employment and changes the agency asks you to report.
2. At full retirement age
SSDI automatically converts to retirement benefits. As a result, you generally do not file a new retirement application. Social Security says the amount remains the same, although ordinary adjustments such as a cost-of-living increase or Medicare premium withholding can affect the net deposit.
3. After conversion
You are receiving retirement benefits. Disability-specific medical eligibility and SSDI work incentives no longer determine the retirement payment. Moreover, because you have reached full retirement age, the retirement earnings test no longer withholds benefits based on wages.
How to find your full retirement age
| Birth year | Full retirement age |
|---|---|
| 1943–1954 | 66 |
| 1955 | 66 and 2 months |
| 1956 | 66 and 4 months |
| 1957 | 66 and 6 months |
| 1958 | 66 and 8 months |
| 1959 | 66 and 10 months |
| 1960 or later | 67 |
Importantly, full retirement age is separate from Medicare eligibility age. Most people become eligible for age-based Medicare at 65, while Social Security full retirement age is now between 66 and 67.
What stays the same
- The underlying earnings record. Both benefits are tied to your Social Security work record.
- The gross monthly amount, generally. The automatic conversion itself usually does not reduce or increase it.
- Cost-of-living adjustments. Social Security applies future COLAs under the program’s rules.
- Direct deposit. The payment generally continues to the account on file.
- Federal tax treatment framework. Retirement, survivor and disability Social Security benefits are considered Social Security benefits for federal tax purposes. Whether part is taxable depends on combined income and filing status.
What changes
| Before conversion | After conversion |
|---|---|
| Payment is classified as SSDI | Payment is classified as retirement |
| Medical continuing-disability rules can apply | Retirement benefits do not depend on proving disability |
| SSDI trial-work and extended-eligibility rules may apply | Disability work incentives no longer govern the payment |
| Work must be evaluated under SSDI rules | At full retirement age, wages do not trigger the retirement earnings test |
| Benefit verification identifies disability benefits | Future verification identifies retirement benefits |
What happens to Medicare?
Meanwhile, many SSDI beneficiaries become eligible for Medicare after the applicable disability waiting period. Consequently, reaching full retirement age does not ordinarily make that Medicare coverage disappear. By then, the beneficiary is also past the standard Medicare eligibility age of 65.
Even so, review the first notice and bank deposit after the conversion. Medicare Part B, Part D or Medicare Advantage premiums can affect the amount deposited. Higher income can also produce an income-related monthly adjustment amount. The label change from disability to retirement is not itself a new Medicare enrollment decision.
The most important exception: early retirement while a disability claim is pending
For example, a person age 62 or older may be able to start reduced retirement benefits while Social Security decides an SSDI claim. Although that can provide income sooner, it is not automatically harmless.
If the disability claim is approved, then Social Security can pay the higher benefit beginning with the first month disability benefits are payable. However, receiving reduced retirement for months before disability entitlement can leave a reduction in the final disability amount. Social Security describes the reduction as less than 1% for each month retirement was received before the first month disability was due.
Before choosing early retirement during an SSDI claim, ask Social Security:
- What is the reduced retirement amount?
- What month could SSDI begin if the claim is approved?
- How would the interim retirement months affect the final amount?
- Could dependent or survivor benefits change?
- What happens if the disability claim is denied or delayed?
Working before and after the transition
Before full retirement age, however, work can affect SSDI even when the conversion date is approaching. In 2026, a trial work month is generally triggered by more than $1,210 in earnings before taxes, or more than 80 hours of self-employment. After the nine-month trial work period, the 36-month extended period of eligibility uses substantial-gainful-activity rules. The 2026 amount is $1,690 per month for a nonblind beneficiary and $2,830 for a beneficiary who is blind. These amounts change over time, and work expenses or subsidies can affect the calculation.
After the automatic conversion at full retirement age, by comparison, the SSDI work-incentive structure no longer controls the retirement benefit. Wages can still affect income taxes, Medicare premiums and the household plan. Nevertheless, Social Security’s retirement earnings test no longer applies once full retirement age is reached.
A 90-day transition checklist
- Confirm the exact full retirement age month. Use your birth date, not a general assumption that retirement age is 65.
- Review your benefit-verification letter. Save a copy before and after the conversion.
- Check direct deposit and contact information. Correct them in your personal Social Security account if needed.
- Report unresolved work activity. Do not assume an approaching retirement conversion erases earlier SSDI reporting duties.
- Keep the conversion notice. Compare the gross benefit, deductions and net deposit.
- Review Medicare deductions. Identify Part B, Part D or other premium withholding.
- Revisit taxes. Estimate combined income using household earnings, pensions, interest and retirement-account withdrawals.
- Review family benefits. Ask about any spouse, child, survivor or auxiliary payment tied to the record.
- Update the retirement plan. Replace “SSDI” with “retirement benefit” in the income plan, but do not invent a benefit increase that the conversion does not create.
Three mistakes to avoid
Mistake 1: expecting a second benefit
You cannot collect full SSDI and a retirement benefit on the same earnings record at the same time. The conversion changes the program category; it does not stack a second check on top.
Mistake 2: filing a new retirement application automatically
The normal SSDI conversion is automatic. Instead, contact Social Security if the notice is wrong, if another benefit is involved or if your situation is unusual, but do not assume everyone must submit a fresh claim.
Mistake 3: ignoring an unresolved notice
Finally, an overpayment, work review, family-benefit issue or Medicare deduction can continue across the transition. Keep records and answer requests by their deadlines.
Related RetireNerd guides
- When Health Forces You to Retire Early: What to Check Before You Stop Working
- How Social Security Calculates Your Benefit
- How to Check and Correct Your Social Security Earnings Record
- Social Security for Self-Employed Workers
- Should You Claim Social Security and Keep Working?
Official sources
- SSA: Disability benefits at full retirement age
- SSA: Disability eligibility and automatic conversion
- SSA: Reduced retirement while waiting for a disability decision
- SSA: Find your full retirement age
- SSA: Working while receiving disability benefits
- IRS: Federal taxation of Social Security retirement and disability benefits
This article provides general educational information. Social Security decisions can depend on entitlement dates, work history, family benefits, other public disability payments and prior claims. Confirm your individual record and any deadline directly with the Social Security Administration.